
The IMF released its updated World Economic Outlook this morning at 9AM.
Global Scenarios
They have a reference forecast (global growth at 3.1%) based on an assumption of a quick end to the conflict in the Middle East. They say that global GDP growth would have been 3.4% had the conflict not occurred, meaning the war has already cost about a third of a point of growth.
However, they offer two alternative scenarios in the event the conflict continues or worsens. While they stressed that the world is not yet in the adverse scenario ($100/barrel oil, global growth drops to 2.5%) or severe scenario ($110–125/barrel oil, global growth near recession at 1.8%), they suggest we are drifting close to the adverse scenario.
The adverse scenario is bad for most emerging markets, particularly any net energy importers.
During the press conference about this report, the speakers suggested that if the US-Iran conflict stops today, the shock would already be comparable to the oil shock in the 1970s. While the global economy is less dependent on oil, the fear is that further oil supply cuts - i.e., this conflict and the Strait of Hormuz closure continue for another few weeks - will make this shock worse than in the 1970s.
The IMF said Central Banks should have learned from the 1970s and are expected to avoid inflation and wage spirals caused by the oil price spikes. While they don’t recommend that Central Banks hike immediately, they expect countries to be vigilant. In reality, they were warning Central Banks against cuts and hinting that interest rate hikes are likely.
On Latin America
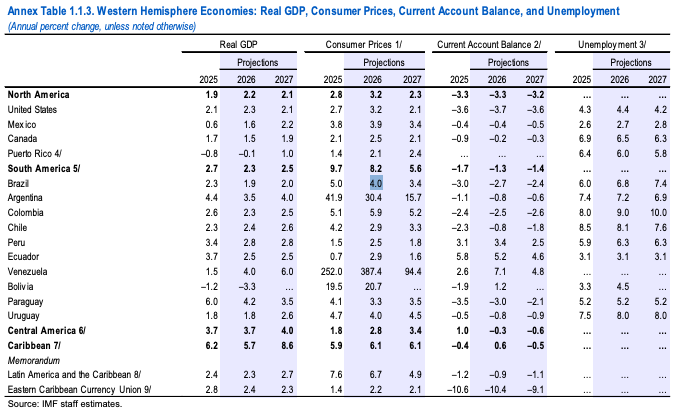
The region is expected to grow 2.3% in the reference scenario, but that will drop if the global scenario goes to the adverse or severe scenarios.
Further, the drop won’t be evenly distributed. The energy exporter/importer divide is the story. The IMF flags that low-income net energy importers face cumulative growth downgrades of 0.5 percentage points over 2026–27, while net energy exporters (Brazil and Venezuela) should see positive or neutral revisions. That is quite bad for Central America and the Caribbean. In many ways, the IMF’s adverse scenario forecast matches my map from late March.
Brazil is a net energy exporter and major user of renewable energy, meaning it will benefit from any oil price spike in 2026. For 2026, Brazil’s growth projection was upgraded to 1.9%, reflecting both stronger-than-expected 2025 performance and a short-term energy price boost from the conflict. However, reality will catch up in 2027, and the economy may slow down due to inflation and fertilizer prices.
On the other hand, the IMF downgraded its projections of GDP growth in Argentina to 3.5% in 2026. They expect 30% inflation. If you go back a full year to the IMF’s Spring 2025 outlook, you’ll see their 2026 projections were 4.5% growth and 15% inflation. That’s an enormous miss on their projections last year, and I’d suggest they remain overly optimistic yet again this year (see my recent newsletter on why the Strait of Hormuz conflict hurts Argentina’s political situation).
Mexico is expected to grow 1.6% this year, which is a slight improvement largely due to the impact of US tariffs not being as bad as forecast last year. That’s still bad for Sheinbaum. The forecast seems to predict a USMCA continuation, meaning any disruption in the negotiation process would mean an even worse outlook for Mexico.
Colombia is expected to have 2.3% growth, 5.9% inflation, 9% unemployment. That is the economy of an anti-incumbent environment.
The key takeaway for me was the scenarios. The 2026 and 2027 economic forecasts for Latin America are ok, not great, in the reference scenario. But outside Brazil, there is significant downside risk for most countries if the conflict in the Middle East continues. Lower growth and higher inflation in the adverse or severe scenarios will drive greater political instability.